The EMC and VMware Arbitrage
 A while back Toro explored an intriguing qeustion: Is there a pricing discrepancy between EMC and VMware? EMC is a data storage company and until this year VMware was its wholly owned subsidiary. VMware of course was one of the most hyped tech IPO's in recent memory and their virtualization solutions are utilized by ALL of the Fortune 500. EMC spun out a stake in VMware earlier this year though VMware is still 87% owned by EMC. Therefore we would expect there to be a fairly strong link between the stock prices of EMC and VMW, and if the link was weak we would expect there to be an arbitrage opportunity. Check out Toro's take below. I have updated his numbers to reflect mid-day prices today. As you can see EMC has become more attractive relative to VMW as VMW's stock price has surged:
EMC (EMC) is a data storage company, and VMware (VMW) makes nifty cool virtualization "solutions" that are going to make pretty much all hardware obsolete, or so I'm told. I'll leave all the fancy explanations to others who know more about this stuff than I do. Instead, I'm interested in the value arbitrage between the two.
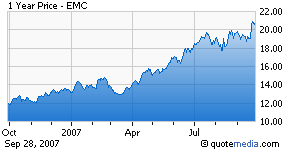
EMC spun-out VMware last month, and currently owns 87% of VMware. Often times, a disconnect occurs in spin-offs, where the market does not properly value either the parent (EMC), or the stub (VMW).
It may seem a bit odd to use the word "value" when describing VMW. I'm not going contest this, since I generally poke around in the value space. I'll leave whether or not VMW trading at 88x 2008 (* note this is now over 100x 2008 earnings) estimates is "value" to the hyper-octane guys. Not that, I'm sure, they care.
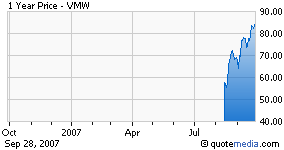
I love spins. It is one area of the market where wide inefficiencies can still reside. To determine whether there is inefficiency in EMC/VMW, we need to calculate the value of EMC excluding its holdings in VMW. If the implied value of EMC is too low, then there is an investment opportunity arising from the spin.
In order to calculate the value of EMC ex-VMW, we back out the value of VMW held by EMC and the income generated by VMW, and find a multiple for EMC-ex VMW.
EMC has 2.12 billion shares outstanding, and a sports a market cap of $43.8 billion (*$45.7 billion) that was based on Thursday's closing price of $20.66 (*$21.81). VMW has 332,500,000 shares outstanding, and on Thursday, VMW closed at $82.36 (*$101.61). As a result, the market cap of VMW currently stands at $27.4 billion (* $38.9 billion). EMC's share of that market cap is $23.8 billion (*$33.84 billion), so EMC ex-VMW is valued at $20.0 billion (*$11.86 billion) by the market.
Analysts estimate that EMC's earnings will be $0.68 this year, $0.83 in 2008, and $0.99 in 2009. Its total profits are expected to be $1.44 billion in 2007, $1.75 billion in 2008 and $2.11 billion in 2009. Analysts have pegged VMW earnings at $0.65 this year, $0.94 in 2008, and $1.39 in 2009. Its total profits for the next three years are expected to be $216 million, $313 million and $460 million respectively.
Because EMC owns 87% of VMW, the financial results of VMW are consolidated on the financial statements of EMC. Therefore, 87% of VMW's profits for the next three years equals $188 million, $272 million and $401 million, respectively. Backing out the VMW profits yields expected net income for EMC excluding VMW of $1.25 billion this year, $1.48 billion in 2008, and $1.71 billion in 2009, which equates to an 18% annual growth next year, and 16% the following year.
By dividing the implied EMC ex-VMW market cap of $20.0 billion (*11.86 billion*) by the total expected EMC profits ex-VMW gives us forward multiples of 16.0x (*9.5x*) for 2007, 13.5x (*8x*) in 2008, and 11.7x (*6.9x*) for 2009.
When considering the growth in EMC's business over the next few years, those valuations look attractive to me (Now they are a steal!). It is also attractive when comparing to other large technology hardware companies such as Hewlett-Packard (HPQ) and Dell(DELL), which are trading at 15.6x, and 17.3x 2008 estimates respectively, and 13.8x and 15.5x 2009 estimates respectively.
At 15x 08 earnings, EMC is worth $21.68, which is a 5% gain. At 17x, EMC is worth $23.07, or a 12% gain. That's okay, but not spectacular. If you had put this trade on the previous Friday, when EMC was $19, your potential gains would have been 15%-20%.
Ideally, to lock in the arbitrage, you would short VMW by 54% of the value of your EMC holding ( $23.8 billion / $43.8 billion), and short another comp, such as a tech ETF or maybe HPQ and DELL, by the value of your remaining position. However, VMW shares will be difficult to short considering the small float.
Disclosure: I have not taken a position in either EMC not VMW, though I may in the future.
Hat Tip: Toro


2 comments:
check your math
I will . . . sorry about that, tried to do that entire post in 10 minutes and should have double checked it.
I'll get it fixed soon.
-Ryan
Post a Comment